
HMO licence cost in London: council fees and what else you’ll pay for
Published: November 13, 2026 Last update: November 13, 2026 Views: 30
Budgeting for an HMO licence can feel like trying to hit a moving target. You look up the cost, find a number that seems reasonable, then discover your council charges something completely different. Add a few compliance certificates, a fire risk assessment, and suddenly you’re spending far more than you expected. It’s genuinely frustrating, especially when you’re trying to plan your finances properly.
The honest truth is that HMO licence cost varies more than most landlords realise, and the headline fee is rarely the whole story. This post breaks down what you’ll pay, why it differs between councils, and what else to budget for so there are no nasty surprises.
TL;DR- HMO licence fees vary significantly between councils, with no fixed national rate.
- Many councils split the fee into two parts: an application fee paid upfront and a licence issue fee paid on approval.
- London boroughs tend to charge more than smaller or rural councils, though some cities outside London are just as expensive.
- The licence fee itself is just one part of the total cost – fire safety, gas, electrical, and property upgrades add up quickly.
- Accredited landlords can sometimes access discounted licence fees through their local council.
- Application fees are typically non-refundable, even if your licence is refused.
- Thorough upfront budgeting is essential, the full cost of compliance is almost always higher than the licence fee alone.
- HMO licence fees vary significantly between councils, with no fixed national rate.
- Many councils split the fee into two parts: an application fee paid upfront and a licence issue fee paid on approval.
- London boroughs tend to charge more than smaller or rural councils, though some cities outside London are just as expensive.
- The licence fee itself is just one part of the total cost – fire safety, gas, electrical, and property upgrades add up quickly.
- Accredited landlords can sometimes access discounted licence fees through their local council.
- Application fees are typically non-refundable, even if your licence is refused.
- Thorough upfront budgeting is essential, the full cost of compliance is almost always higher than the licence fee alone.
For a five-bedroom HMO, licence costs across England typically run from roughly £900 to £1,900 for a five-year term, depending on your local council, and some London boroughs charge more. There’s no single national fee, each council sets its own rate, and those rates reflect the council’s administrative and inspection costs for running the licensing process.
That range is wide, and it catches landlords off guard. A landlord with properties in two different towns might pay very different amounts for what is essentially the same type of licence. It’s not arbitrary, but it can feel that way when you’re on the receiving end.
In general, London boroughs and some larger cities charge more than smaller or rural councils. Areas with a lot of shared housing can receive more applications and need more resource to process them, and a council that sends an officer out for an in-person inspection spends more per licence than one that relies on a documentary review.
London fees are set borough by borough, and the gaps are wide. As of November 2026, published fees for a mandatory licence on a five-room HMO include about £1,475 in Croydon (five rooms at £295 each), £1,493 in Kensington and Chelsea, £1,827 in Wandsworth and £2,750 in Lambeth (five rooms at £550 each). Croydon and Lambeth charge per habitable room, so every extra room adds to the bill. Kensington and Chelsea charges a flat fee for up to five units plus £72 for each one above that, while Wandsworth sets its fee by number of bedrooms.
Fees can change at each council’s annual review, and several of these took effect on 1 April 2026, so check your borough’s current schedule before you budget. Also check whether living rooms count towards the room total, because that can change what you pay.
Outside the capital, fees vary widely: some larger cities charge as much as London boroughs, while smaller towns and rural councils can come in under £1,000.

Most councils don’t charge one flat fee. They split the HMO licence application into two separate payments, collected at different stages. Understanding this structure helps you plan your cash flow and avoid confusion mid-application.
This is paid when you submit your application. It covers the administrative cost of processing paperwork, reviewing documents, and carrying out initial checks. It’s non-refundable in almost all cases. If your application fails or you withdraw it, you won’t get this money back. That’s worth knowing before you apply.
This is paid once your application has been assessed and the council is ready to grant the licence. Some councils only collect this on approval; others take a combined total upfront. How the total is divided between the two parts varies from council to council.
Some councils add a charge for each lettable bedroom on top of the base fee. This is common in London boroughs and used by some councils elsewhere. It means a larger HMO will cost noticeably more to licence than a smaller one, even within the same council area.
Here’s a summary of the typical fee components to expect:
- Application fee (Part A) paid on submission, usually non-refundable
- Licence issue fee (Part B) paid on approval or combined upfront
- Per habitable room charge added to the base fee in some councils
- Renewal fee charged at the end of the licence period, typically five years
- Additional licensing fees for smaller HMOs, or selective licensing fees for other lets, where your council runs those schemes
One thing that trips landlords up is assuming the fee they paid five years ago still applies. Councils review their fee structures regularly, so the amount can change between applications. Renewal fees are sometimes lower than the original fee, but don’t count on it: check the current fee schedule before you budget.
It’s tempting to assume there’s some injustice happening when you discover your neighbouring landlord pays half what you do for the same type of licence. But the variation isn’t random. It comes down to a few predictable factors.
- Local housing demand. Councils in areas with high concentrations of shared housing, students, or young professionals process a larger volume of HMO applications. That can create operational pressure on licensing teams, and fees tend to reflect it.
- Council administrative costs. Some councils carry out more thorough inspections or use more resource-intensive processes. Those costs get factored into the fee. A council that sends an officer out for an in-person inspection is spending more than one that relies on a documentary review.
- Selective and additional licensing schemes. Some councils have introduced wider licensing schemes beyond mandatory HMO requirements. If your property sits within a designated area under one of these schemes, it may need an additional or selective licence with its own fee. For HMOs, an additional licence covers properties that fall outside mandatory licensing, so it replaces the mandatory licence rather than being added to it.
London boroughs tend to sit at the top because they combine high demand, dense housing stock, and high operating costs, and several add per-room charges on top. A council with relatively few HMO properties can charge less, because the administrative burden is lighter.
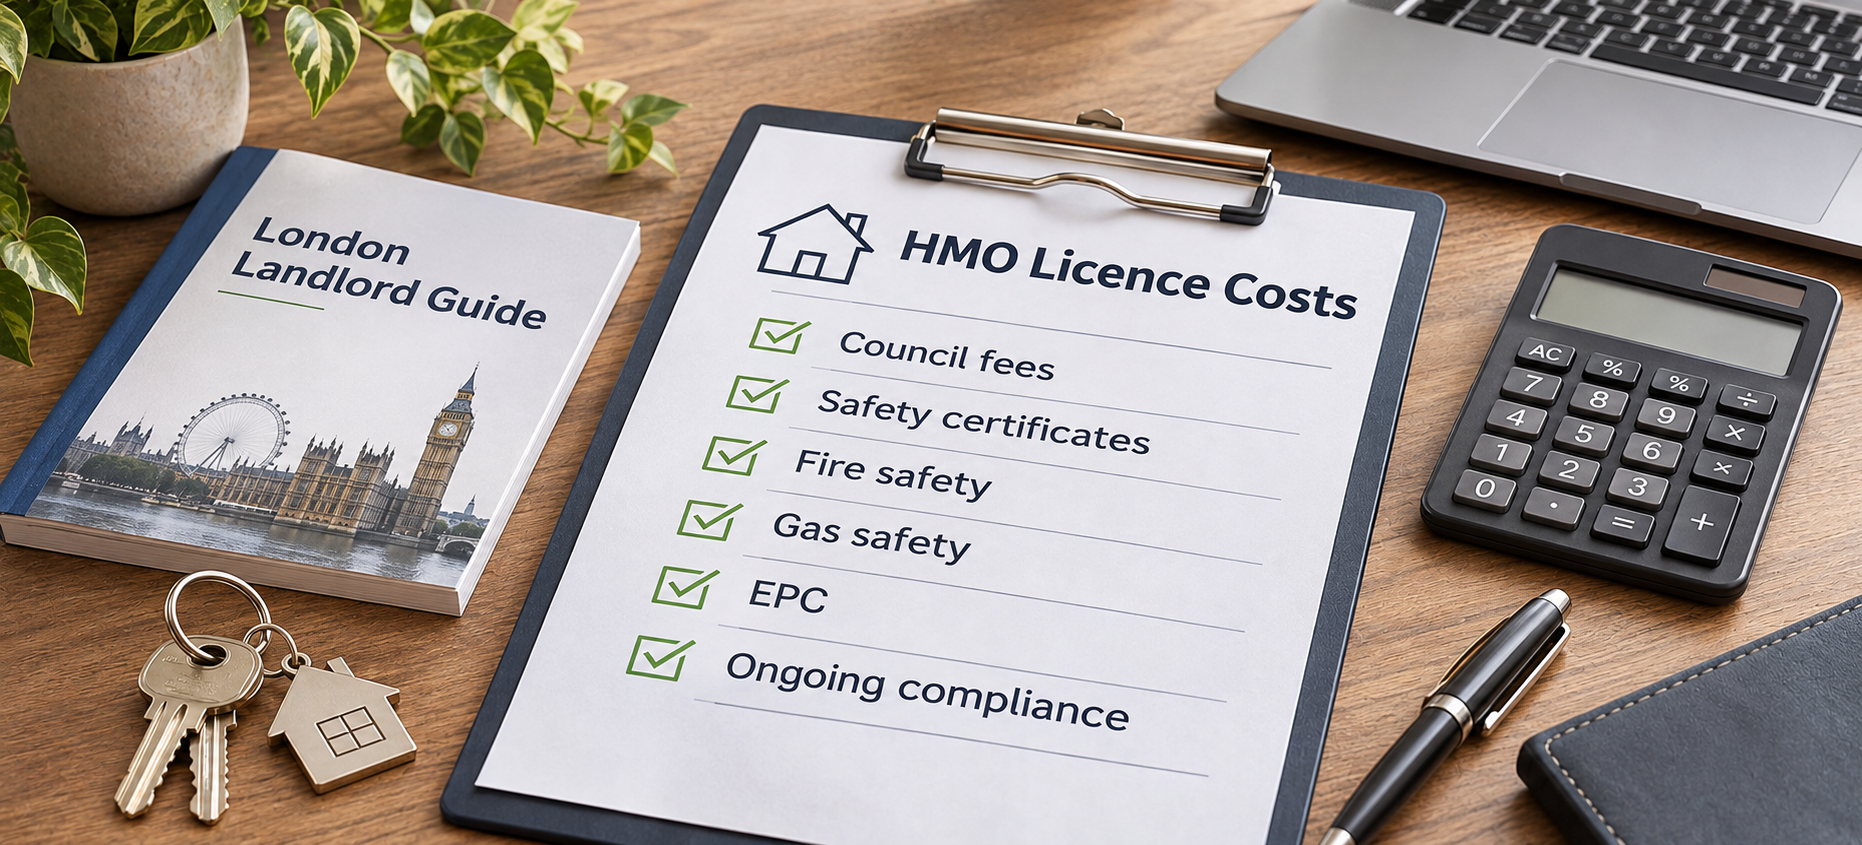
This is where a lot of landlords get caught out. They budget for the licence fee and forget it’s just the entry ticket. The real cost of getting an HMO up to standard includes a range of additional expenses that can dwarf the licence fee itself.
Here’s what you should actually be budgeting for:
- Fire risk assessment: the Regulatory Reform (Fire Safety) Order 2005 requires one for the shared parts of an HMO, and it should be carried out by someone competent. The cost varies depending on property size and complexity.
- Gas safety certificate: required annually, covering all gas appliances and flues. Must be carried out by a Gas Safe registered engineer.
- Electrical Installation Condition Report (EICR): mandatory for HMOs and must be renewed at least every five years.
- Fire safety upgrades: interlinked smoke alarms, heat detectors, fire doors, and emergency lighting are all commonly required. These can be substantial if the property hasn’t been upgraded before.
- Energy Performance Certificate (EPC): required for letting any residential property, with minimum energy efficiency standards applying.
- Legionella risk assessment: landlords must assess the risk from legionella. A formal test certificate isn’t required, but a written record of your assessment is good practice, especially for shared properties with multiple water outlets.
- Minimum room size compliance: HMO regulations specify minimum floor areas for sleeping rooms. If your rooms don’t meet the standard, you’ll need to either reconfigure or reduce occupancy, which directly affects your rental income.
- Amenity standards: adequate bathroom and kitchen facilities per number of occupants. If the property doesn’t meet these, refurbishment costs can be significant.
Fantastic Corporate Services can arrange the certificates and works on this list and help with your application documents, so you can plan the whole budget in one place.
The licence fee and the compliance cost are two very different things. You might apply with a relatively modest licence fee and then discover your property needs new fire doors throughout, an upgraded consumer unit, and additional bathroom facilities. Those costs add up fast, and none of them are optional.
Some councils offer reduced HMO licence fees to landlords who hold accreditation through a recognised scheme, such as those run by local authorities or national bodies like the National Residential Landlords Association. The logic is that accredited landlords have demonstrated a baseline of knowledge and professional conduct.
The discount, where available, varies by council. Not every council offers one at all. Where one exists it is usually modest, typically from tens of pounds up to a couple of hundred, so treat it as a bonus rather than something to plan your budget around. The only way to know is to check with your specific council before you apply.
To benefit from accreditation discounts, councils may ask you to:
- Be a member of a council-recognised landlord accreditation scheme
- Demonstrate completed relevant training or CPD requirements
- Have a clean compliance history with no outstanding enforcement notices
- Provide proof of accreditation status at the point of application
Some councils also take money off for a good EPC rating, or for supplying your gas, electrical and EPC certificates up front, so it’s worth asking what discounts exist.
It’s also worth being clear about refund policies before you submit anything. Most Part A application fees are non-refundable. If your application is refused, the council keeps the processing fee, although some councils don’t charge Part B, or refund it, if the licence is refused. Some landlords are surprised by this, particularly if they assumed a refusal would bring everything back.
If you’re planning to apply across multiple properties or expand your portfolio in the same council area, it’s worth asking whether any bulk or portfolio discounts exist. Some councils publish them and are open to this conversation, especially if you’re bringing several applications at once.
Need help with HMO compliance?
Fantastic Corporate Services can arrange the safety certificates and works your HMO needs.


The HMO licence cost is rarely what it first appears to be. The headline fee varies by council, the structure splits across two payments, some councils add per-room charges, and the full compliance picture sits beneath all of that. Landlords who go in with only the licence fee in mind tend to get a rude awakening somewhere along the way.
Plan for all of it. Research your council’s specific fee schedule, factor in every required certificate and safety upgrade, and check whether accreditation gives you any leverage on the fee. The landlords who manage HMO compliance well aren’t the ones who got lucky. They’re the ones who did their homework first.
Are HMO licence application fees refundable?
In almost all cases, no. The Part A application fee covers the council’s administrative costs and is non-refundable once submitted, regardless of whether your application is approved or refused. Some landlords assume a refusal will come with a refund. The Part A fee is kept, although some councils don’t charge or refund Part B if the licence is refused. Always treat the application fee as a sunk cost from the moment you submit it, and make sure your property is as compliant as possible before applying.
Do all councils charge the same for HMO licences?
No. Each council sets its own fee independently, and there’s significant variation across the country. London boroughs tend to charge the most, while smaller and rural councils can charge noticeably less. The same type of property can attract very different licence fees depending purely on location. Always check your specific council’s current published fee schedule, as rates are updated periodically and figures found elsewhere online can be out of date.
What additional costs should I budget for when getting an HMO licence?
Beyond the licence fee itself, budget for a fire risk assessment, gas safety certificate, Electrical Installation Condition Report (EICR), and a legionella risk assessment. Fire safety upgrades such as interlinked alarms, fire doors, and emergency lighting are commonly required. If the property doesn’t meet minimum room size or amenity standards, refurbishment costs can be substantial. The total compliance cost often exceeds the licence fee significantly.
How long does an HMO licence last before it needs renewing?
HMO licences are typically granted for up to five years, though councils can issue them for shorter periods if there are outstanding compliance concerns. At renewal, councils often charge a fresh fee, and the amount can differ from what you originally paid, so check the current fee schedule. It’s worth noting your renewal date well in advance.
Popular posts
Week
Month